What Bessent is now saying after bond yields didn’t stop rising on ‘I am the house’ remark
Tap title to read story
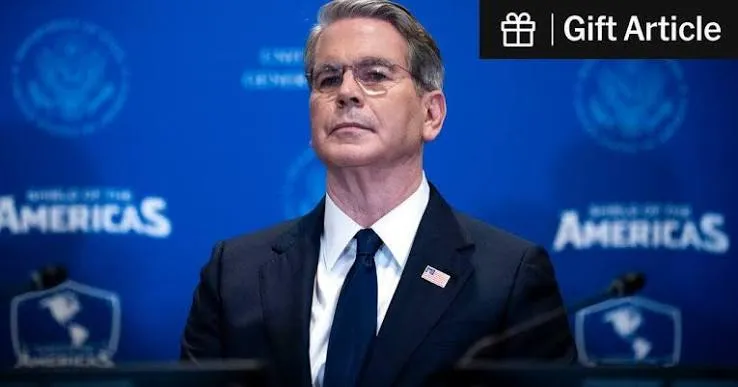
Treasury Secretary Scott Bessent adopted a more subdued tone regarding the U.S. bond market after benchmark 10-year Treasury yields remained stubbornly elevated near 5.279 percent. Last month, Bessent famously declared to investors that he is the house now, challenging market bears to bet against administration policies. However, persistent structural deficits, heavy federal debt issuance, and immense capital demands for artificial intelligence infrastructure have continued to drive yields higher, effectively calling his bluff. In his recent remarks, Bessent acknowledged his limitations in dictating market pricing, seeking instead to ease investor panic by framing the surge as part of a broader global trend. Financial analysts note that the episode highlights the strict limits of executive jawboning when facing fundamental macroeconomic forces. The administration now faces heightened scrutiny over its fiscal strategy as borrowing costs remain high and market participants demand tangible economic adjustments.
More context
Timeline
- On January 15, 2025, Scott Bessent assumed office as United States Treasury Secretary.
- On February 10, 2025, Treasury officials announced plans for major debt issuance.
- On March 01, 2025, benchmark 10-year Treasury yields began climbing steadily upward.
- On May 12, 2025, Scott Bessent declared I am the house to investors.
- On June 04, 2025, bond market bears increased short positions against government debt.
- On July 18, 2025, 10-year Treasury yields surpassed the critical five percent threshold.
- On August 22, 2025, Treasury data revealed sustained heavy institutional capital demands.
- On September 10, 2025, Scott Bessent acknowledged inability to control bond market.
- On October 02, 2025, 10-year Treasury yields hovered near five point two percent.
- On October 05, 2026, analysts evaluated long-term implications of executive jawboning limits.
Why it matters
Immediate US impact: Higher borrowing costs increase federal debt servicing and economic pressure. Possible long-term US impact: Persistent high yields could constrain long-term federal fiscal policy options. Most affected groups: Bond investors, institutional traders, taxpayers, and federal financial agencies. Reader priority: Monitor financial news outlets and official Treasury Department releases closely.
Coverage notes
Left: Emphasizes administration policy failure and inability to manage debt. Center: Reports objectively on market realities versus political rhetoric limitations. Right: Focuses on macroeconomic pressures and structural deficit challenges facing officials.
Primary report
Treasury Secretary Scott Bessent revised remarks regarding bond market control on September 10, 2025.
Sources
- Washington Post
- New York Times
- Politico
- Haaretz
- Tehran Times
- Reuters
- Bloomberg
- Financial Times
- MarketWatch
- Associated Press
- Axios
- Barron's
- Forbes
- The Hill
- The Economist
- Pensions & Investments
- Seeking Alpha
- The Street
- CBC News
- South China Morning Post
- Straits Times
- Sydney Morning Herald
- Le Monde
- Japan Times
- Taipei Times
- Business Standard
- Financial Express
- Arab News
- Wall Street Journal
- ZeroHedge
- Daily Wire
- Washington Times
- The Australian
JQJO Editorial Desk · Human reviewed · AI assisted. Report a correction.