‘It doesn’t seem fair’: I’m retired and have plenty of money. Why can’t I qualify for a retail credit card?
PUBLISHED Sep 23, 2026, 7:51 AM ET
Read, Watch or Listen
Retired Americans with significant accumulated wealth and strong credit scores report unexpected rejections when applying for retail credit cards. Automated underwriting algorithms utilized by retail card issuers primarily evaluate steady, traditional W-2 salary employment rather than total net worth or liquid assets. Because retirees often derive cash flow from investment drawdowns, pensions, or delayed Social Security claims, paper income metrics frequently trigger automated risk warnings. Financial experts note that applicants can often overcome these automated barriers by properly aggregating all eligible retirement income sources, contacting issuer reconsideration lines to speak directly with human underwriting analysts, or applying for general-purpose rewards cards issued by major traditional financial institutions featuring more flexible evaluation standards.
By Ayesha A. | JQJO News
Timeline of Events
- On January 1, 2010, the Credit CARD Act took effect nationwide regulating lending.
- On May 15, 2018, automated underwriting systems became standard across major retail lenders.
- On November 10, 2021, consumer advocacy groups highlighted retail credit approval disparities.
- On August 14, 2023, financial analysts published reports on retiree asset evaluation flaws.
- On February 20, 2024, credit bureaus updated score modeling for non-traditional income streams.
- On July 12, 2024, retail lenders integrated stricter cash-flow verification software tools.
- On October 5, 2025, consumer complaints regarding asset-based card denials increased significantly.
- On January 18, 2026, financial advisors recommended manual reconsideration processes for retirees.
- On May 30, 2026, major credit card issuers evaluated alternative income verification frameworks.
- On September 22, 2026, industry reports confirmed ongoing friction for wealthy retirees applying.
- Expectations indicate lenders will gradually adopt broader asset-based underwriting models soon.
News Intelligence
- Immediate US impact: Wealthy retirees face unexpected credit application rejections nationwide today.
- Possible long-term US impact: Lenders may reform automated underwriting standards for asset evaluation.
- Most affected groups: Wealthy retirees, retail lenders, credit card issuers, and consumers.
- Reader priority: Review income aggregation methods and utilize issuer reconsideration phone lines.
- Articles Published:
- 32
- Right Leaning:
- 2
- Left Leaning:
- 4
- Neutral:
- 26
- Distribution:
- Left 13%, Center 81%, Right 6%
Left: Emphasizes systemic algorithmic bias impacting vulnerable senior consumer populations. Center: Reports objectively on algorithmic lending mismatches affecting wealthy retirees. Right: Focuses on individual financial documentation and traditional income verification standards.
Published report detailing retiree credit card denials on September 22. https://www.marketwatch.com/story/it-doesnt-seem-fair-im-retired-and-have-plenty-of-money-why-cant-i-qualify-for-a-retail-credit-card-bb615735
Coverage of Story:
From Left
The paper income problem: Why retirees are failing automated card checks
Washington Post New York Times San Francisco Chronicle The AtlanticFrom Center
The Credit Card Rejection Trap Facing Wealthy Retirees
Wall Street Journal Bloomberg MarketWatch Reuters Associated Press Forbes USA Today Chicago Tribune The Hill MarketWatch Barron's Time Newsweek U.S. News & World Report The Street Bankrate The Motley Fool Quartz The Dallas Morning News Houston Chronicle The Seattle Times Miami Herald Detroit Free Press Star Tribune The Arizona Republic The OregonianFrom Right
Senior citizens face automated wall when applying for retail store cards
The Washington Times Daily Wire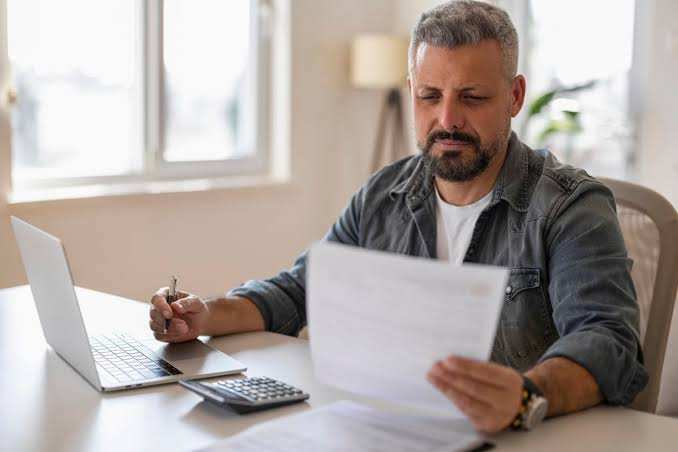

Comments