How to avoid the ‘widow tax’ and other financial headaches if your spouse dies
Tap title to read story
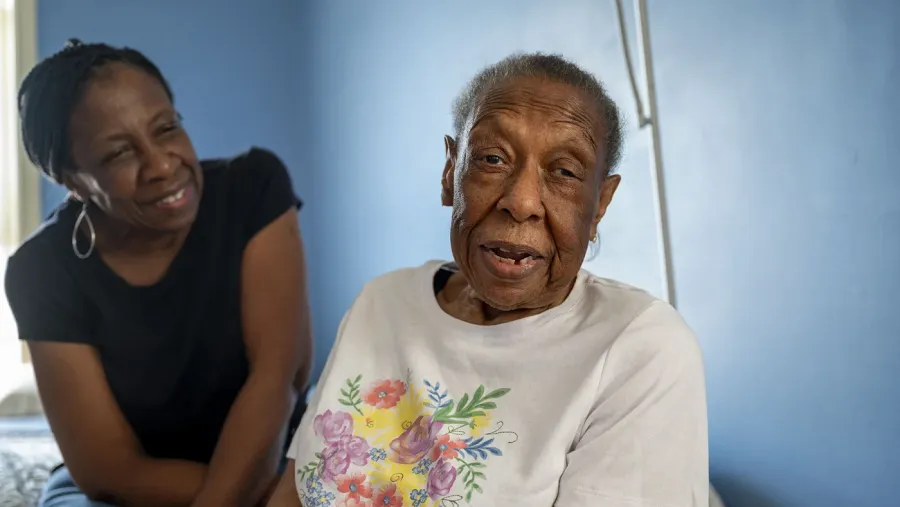
Losing a spouse brings profound emotional distress, frequently accompanied by an immediate financial burden known as the widow tax penalty. Married couples filing jointly benefit from wide tax brackets and high standard deductions under Internal Revenue Service rules. Following the death of a spouse, surviving taxpayers typically transition to single filing status, resulting in compressed tax brackets and reduced deductions. This structural shift can inflate income tax liabilities even when overall household earnings decline. Additional financial friction arises from potential increases in Medicare income-related monthly adjustment amounts due to lower single filing thresholds. Proactive financial planning strategies, including strategic Roth conversions, optimized retirement account distributions, and comprehensive survivor benefit evaluations, help mitigate sudden tax spikes and protect surviving spouses from unexpected fiscal strain.
More context
Timeline
- On January 1 2018 Tax Cuts and Jobs Act altered individual tax brackets significantly.
- On January 1 2026 Current IRS single and joint filing brackets remained actively enforced.
- On September 20 2026 Financial analysts published modern guidance regarding survivor tax penalties.
- On September 21 2026 Retirement planners recommended proactive Roth conversions for married couples.
- On September 22 2026 Advisors highlighted Medicare premium adjustments affecting surviving single filers.
- On September 23 2026 Experts urged early estate coordination to reduce future burdens.
- On October 1 2026 Tax professionals anticipate expanded legislative discussions regarding survivor brackets.
- On January 1 2027 Demographic shifts will increase surviving spouse populations nationwide.
- On January 1 2028 Federal agencies may review single filer income thresholds further.
- On January 1 2030 Retirement income planning models will incorporate broader widow tax mitigation.
Why it matters
Immediate US impact: Surviving spouses face immediate income tax increases and healthcare surcharges. Possible long-term US impact: Long-term retirement security requires proactive multi-year tax bracket management. Most affected groups: Widows, widowers, financial planners, and estate attorneys are most affected. Reader priority: Readers should prioritize verified tax guidance over general social commentary.
Coverage notes
Left: Emphasizes systemic wealth protection and equitable tax structures for survivors. Center: Focuses on objective financial mechanics and standard tax planning strategies. Right: Highlights individual responsibility and private wealth preservation through proactive planning.
Primary report
Financial planning advisory published detailing survivor tax penalty mitigation strategies.
Sources
- The Washington Post
- The New York Times
- MarketWatch
- Forbes
- The Wall Street Journal
- Reuters
- Bloomberg
- USA Today
- Bankrate
- U.S. News and World Report
- ThinkAdvisor
- Financial Advisor Magazine
- Barron's
- Time
- NBC News
- NPR
- Chicago Tribune
- Houston Chronicle
- Miami Herald
- Seattle Times
- San Francisco Chronicle
- Dallas Morning News
- Detroit News
- Cleveland Plain Dealer
- Arizona Republic
- St. Louis Post-Dispatch
- Minneapolis Star Tribune
- Baltimore Sun
- Orlando Sentinel
- Indianapolis Star
- Sacramento Bee
- Pittsburgh Post-Gazette
- Cincinnati Enquirer
- Kansas City Star
- The Plain Dealer
- cnbc.com
JQJO Editorial Desk · Human reviewed · AI assisted. Report a correction.