Pulte’s FHFA to Ease Credit Data Rule for Fannie, Freddie
Tap title to read story
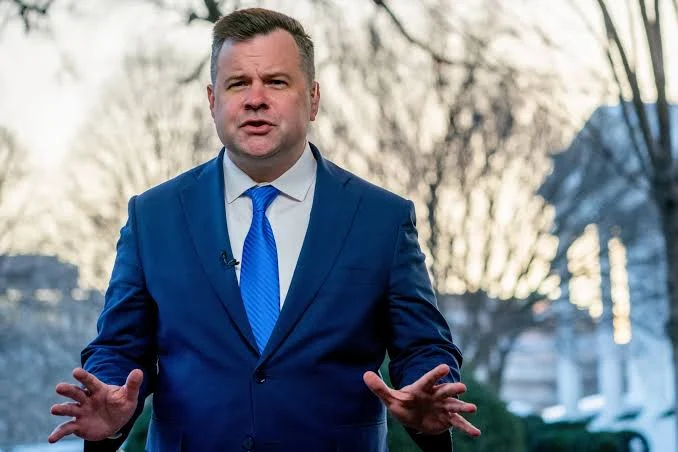
The Federal Housing Finance Agency is preparing to relax credit data requirements for Fannie Mae and Freddie Mac by replacing the traditional tri-merge credit report model with a two-bureau model. Under the proposed framework, mortgage lenders selling loans to government-sponsored enterprises may soon pull credit data from only two major credit reporting bureaus instead of three. FHFA Director Bill Pulte is expected to detail the policy during an upcoming mortgage industry conference in Chicago. Following the reports, shares of major credit reporting and scoring companies experienced notable after-hours pullbacks amid ongoing agency efforts to introduce market competition and lower transaction costs for prospective borrowers. Industry stakeholders remain divided over potential cost savings versus underwriting risk implications, as financial analysts debate whether removing a credit bureau could obscure critical debt obligations or past derogatory credit events for lenders.
More context
Timeline
- On September 15, 2026, FHFA leadership initiated preliminary reviews regarding mortgage credit report standards.
- On September 20, 2026, agency officials evaluated potential cost reductions for prospective home loan borrowers.
- On September 25, 2026, market analysts anticipated upcoming regulatory adjustments affecting major credit scoring agencies.
- On September 28, 2026, shares of credit reporting companies experienced notable after-hours trading pullbacks.
- On September 30, 2026, industry stakeholders debated underwriting risk versus consumer cost savings.
- On October 1, 2026, preparations intensified for Director Bill Pulte's upcoming Chicago conference address.
- On October 2, 2026, financial markets monitored impending regulatory announcements regarding two-bureau credit standards.
- On October 3, 2026, mortgage lenders reviewed potential operational adjustments for future loan processing.
- On October 4, 2026, policy experts analyzed expected impacts on secondary mortgage market liquidity.
- On October 5, 2026, stakeholders prepared for formal policy disclosures at the industry conference.
Why it matters
Immediate US impact: Lowers upfront credit check costs for prospective mortgage loan borrowers. Possible long-term US impact: Increases market competition among major credit reporting and scoring firms. Most affected groups: Mortgage lenders prospective homebuyers credit reporting agencies and financial institutions. Reader priority: Monitor official FHFA conference announcements and subsequent regulatory filing documents.
Coverage notes
Left: Highlights potential consumer savings and challenges to corporate credit monopolies. Center: Reports regulatory updates market reactions and stakeholder debates with neutral balance. Right: Emphasizes market competition reduction of transaction costs and underwriting risks.
Primary report
Federal Housing Finance Agency prepared credit data rule changes on October 2 2026
Sources
- Politico
- Washington Post
- The Atlantic
- HuffPost
- Reuters
- Bloomberg
- Financial Times
- MarketWatch
- Associated Press
- The Hill
- Barron's
- Forbes
- National Mortgage Professional
- Mortgage Banker Magazine
- The Street
- Seeking Alpha
- Benzinga
- Quartz
- Axios
- Chicago Tribune
- Dallas Morning News
- Miami Herald
- San Francisco Chronicle
- Houston Chronicle
- Seattle Times
- Detroit News
- Phoenix Business Journal
- NPR News
- USA Today
- Newsweek
- Time
- The Wall Street Journal
- Washington Times
- The Daily Caller
JQJO Editorial Desk · Human reviewed · AI assisted. Report a correction.